

The Net Errors and Omissions (NEO) item has been one of the most debated components of the Balance of Payments Statistics in recent years. Having taken high positive values in 2021 and 2022, this item has been on a significantly negative trajectory since 2023. This has naturally raised the following question: Does the negative accumulation in the NEO point to unrecorded foreign trade transactions or the gaps in the measurement and coverage of financial accounts?
The Balance of Payments Statistics are prepared by compiling data on international trade and financial transactions from different data sources. The use of different data sources may lead to differences in valuation, measurement, classification, and time of recording. Such differences are reflected as a “residual” in the NEO. Thus, the NEO may stem either from inadequate measurement of current transactions or from incomplete recording of some transactions in the Financial Account.
The three revisions to the Financial Account, which the Central Bank of the Republic of Türkiye announced with the press release of July 24, 2026 and took effect starting from the release of June 2026 Balance of Payments Statistics on August 13, 2026, offer a significant finding in this respect. In this blog post, we examine the grounds for the revisions explaining a substantial part of the recent negative trend in NEO, along with their consequences in terms of the balance of payments.
Use of New Data Source to Compile Residents’ Deposits Abroad
The first revision is related to the compilation of data on residents’ deposits abroad. Overseas deposits of households and non-bank financial corporations residing in Türkiye are calculated using the quarterly statistics of the Bank for International Settlements (BIS). However, the limited coverage of countries in the BIS data and the difficulty to accurately identify the residency status in certain cases, such as dual citizenship in particular, may lead to incomplete or inaccurate recording of some movements.
For instance, when overseas deposits that cannot be tracked through the existing data source are brought into Türkiye, these deposits are recorded in foreign currency assets of banks in Türkiye but there may not be a corresponding record of the decline in the accounts abroad. Similar measurement differences may also arise in the reverse version of these transactions.
To mitigate these issues, SWIFT data is now used to compile information on the foreign deposit transactions of resident households. This allows for a more accurate assessment of cross-border deposit transfers.
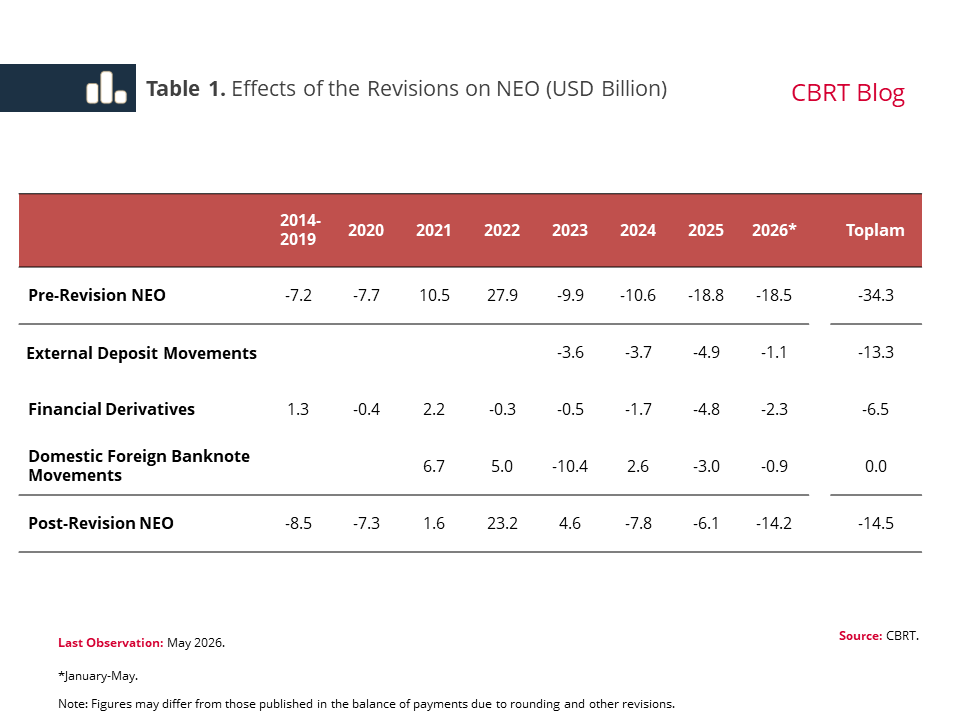
The cumulative effect of this adjustment on the NEO is calculated to be USD -13.3 billion over the January 2023-May 2026 period. This amount does not mean a new outflow of funds, but rather indicates that the movements previously reflected in the NEO are now shown under the accurate item.
Inclusion of Financial Derivatives in the Balance of Payments
The second revision covers the calculation of profits and losses arising from financial derivatives between residents (banks and other sectors) and non-residents. Profits or losses on transactions, such as swaps, forwards, and options, do not stem from the return on the underlying asset but rather from the value of the financial derivative contract. Therefore, these amounts are recorded under the Financial Derivatives item in the Financial Account instead of the Primary Income Balance item (IMF, 2009, para. 11.95).
Due to the different accounting methods used by banks and the technical complexity of the transactions, profits and losses arising from derivative transactions with non-residents could not be fully reflected in the statistics. While the movements in the underlying assets of these transactions were reflected under the banks’ foreign exchange assets, the absence of a corresponding entry regarding profits or losses caused the NEO.
To address data gaps, a contract-based calculation framework has been established based on data from the Central Securities Depository and the Banking Regulation and Supervision Agency. Profits and losses from transactions in foreign currency, precious metals, or Turkish lira have been calculated using the exchange rates and interest rates specified in the contract since 2014. Thus, transactions are shown in the Financial Account consistent with their economic nature.
The cumulative effect of the revision regarding financial derivatives on the NEO is calculated to be a net loss of USD 6.5 billion over the January 2014-May 2026 period (Table 1).
Decomposition of Domestically-Driven Foreign Banknote Movements from External Transactions
The third revision concerns the decomposition of banknotes held by residents, i.e., foreign currency banknotes, according to sources of entry into and exit from the banking system.
Not every foreign banknote transaction in the banking system stems from an external economic transaction. Residents depositing or withdrawing foreign banknotes held outside the financial system affect the banks' foreign currency holdings but do not constitute transactions with non-residents. Therefore, such transactions must be decomposed from external economic transactions.
Under the previous methodology, all foreign banknote movements with no directly identifiable sources were assumed to stem from external transactions. This could lead to significant fluctuations in the NEO item during periods of increased traffic between the “mattress money” holdings and the banking system.
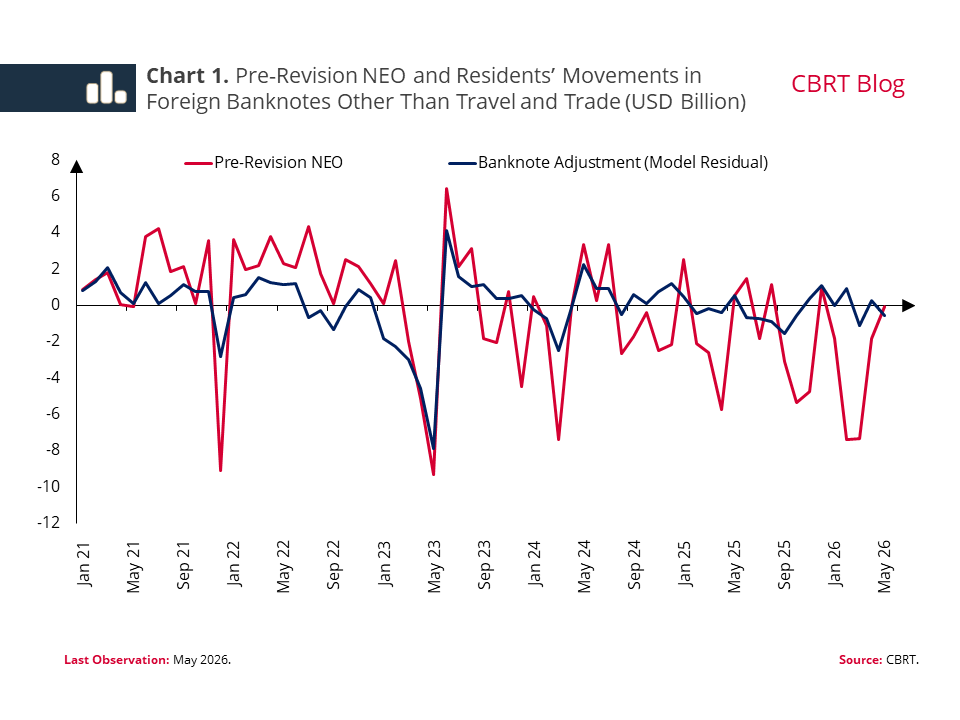
To decompose foreign banknote movements based on source, a regression model[1] has been used at a monthly frequency since 2021. While the portion of net foreign banknote inflows attributable to travel expenditures and cross-border trade through the land borders is considered to be externally driven, the difference between the actual movement and the model estimate (the residual) is treated as domestically-driven foreign banknote movement.[2] The decomposition results show that extreme fluctuations in the NEO item during certain periods stemmed from foreign banknote movements unrelated to external economic transactions (Chart 1). While this revision does not affect the cumulative NEO for the relevant period, it offsets the period-specific NEO figures in absolute terms.
 Total Impact of the Revisions
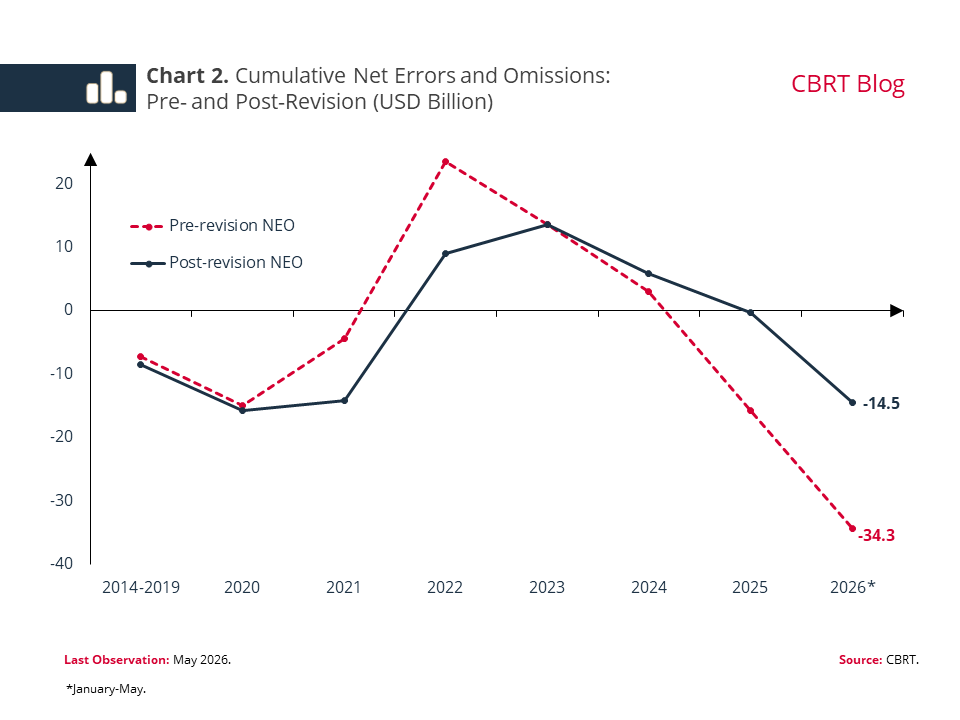
Following the three revisions to the Financial Account, the cumulative NEO for the January 2014–May 2026 period improves from USD -34.3 billion to USD -14,5 billion, moving closer to zero line (Table 1, Chart 2).
Regarding the effects of the revision, two things should be highlighted. Firstly, the revisions do not function only in one direction: they pull the high positive NEO for 2021–2022 down and push the negative NEO for 2023–2025 up. Secondly, the NEO, which reached USD –57.8 billion between 2023 and 2026, the period in which the pre- and post-revision series diverged most markedly, stands at USD –23.5 billion US dollars after the revision. In other words, the source of more than half of the negative accumulation has recently been identified and placed under the relevant Financial Account items. However, in the first five months of 2026, the NHN remains at a relatively high negative level even after the revision. Nevertheless, as the data for this period is still provisional, a more accurate assessment can be made once final figures are available.
 Current Account-Based Assessment and Conclusion
The revisions do not lead to a change in the Current Account Balance; but they ensure that certain amounts previously recorded under the NEO are now placed under the relevant Financial Account items in line with their economic nature. Thus, the current account deficit remains intact, while the reduction in the absolute size of the NEO reveals that a significant portion of the NEO stems from differences in scope, classification, valuation and timing of recording within the Financial Account. Rather than a new inflow or outflow of funds, this change indicates recording of realized transactions under accurate items.
These conclusions confirm that assessments that add the entire NEO to the current account deficit may lead to misleading inferences by relating measurement discrepancies arising from the financial account to foreign trade. The use of new data sources, on the other hand, has strengthened the scope, classification and consistency of the statistics, while providing a sounder foundation for the assessment of the current account deficit and external financing requirements. In this context, efforts to improve data quality are ongoing.
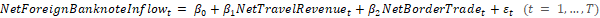
β₀ denotes the constant term; β₁ and β₂ denote the model coefficients; εₜ denotes the error term, and t denotes time. Using the model coefficients obtained from this model estimation, the model residual ( ) is calculated as follows:
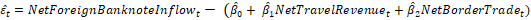
[2] It should be noted that this is not a directly observed data, but rather an estimate based on the model assumptions.